-
Posted by Daily Cargo News
- |
-
09 Nov, 2026
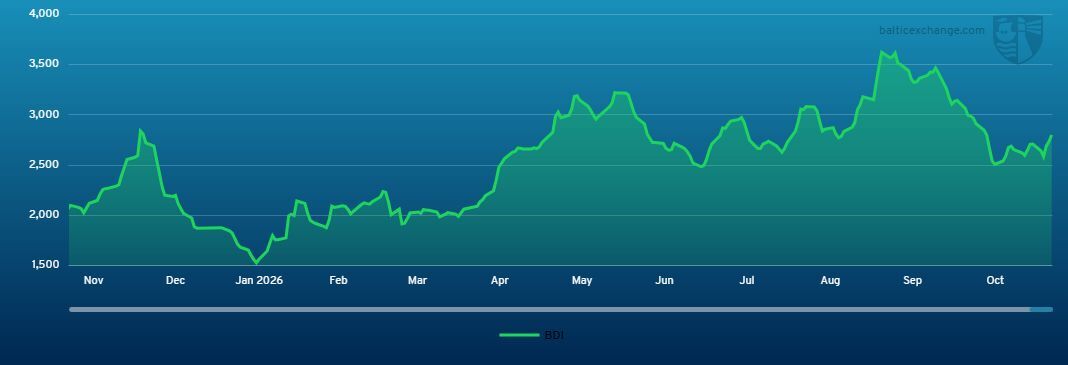
THE BALTIC Dry Index (BDI) recorded a weekly gain of 3.4%, finishing at 2805 points for 6 November 2026, up from 30 October's figure of 2714.
Capesize
The Capesize market experienced a mixed but ultimately firmer week, with an initial period of weakness giving way to improved sentiment and firmer conditions, although momentum remained uneven across the basins. The Pacific was the main source of pressure early on, with C5 falling from $13.80 to the low $13.00s as two miners remained active but consistently tested lower levels. Despite a midweek recovery in sentiment, activity remained selective, with Friday's miner business concluded at $13.25, leaving the route below Monday's opening levels. The South Brazil and West Africa to China markets saw a more pronounced turnaround, recovering from a lack of demand and bids in the early part of the week to a notably active Wednesday when more than 15 C3 fixtures were reported, pushing rates towards $37.00. However, the subsequent slowdown and lower fixtures on Thursday suggested owners were becoming more cautious. The North Atlantic remained the relative outperformer, with stronger transatlantic business lifting the C8 index to $41,000 by Friday, and fresh enquiry emerging across both TA and FH routes. Lower bunker prices also provided some support to TCE earnings towards the latter part of the week. Overall, the market finished the week on a firmer footing, with the BCI 182 opening at $35,944, dipping on Tuesday before recovering steadily to close at $39,395.
Panamax-Kamsarmax
The market began the week on a subdued note before gathering momentum as improving demand and tightening tonnage availability supported firmer sentiment across both basins. In the Atlantic, transatlantic and fronthaul enquiry gradually increased, with rates strengthening as tonnage availability tightened, particularly off the West Mediterranean. However, the North Continent remained comparatively well supplied, limiting broader gains. An 82,000-dwt fixed a transatlantic trip at just below $30,000 basis delivery EC South America, while US Gulf fronthaul business was reported at $24,000 basis North Continent delivery and an EC South America fronthaul fixed at $18,750 basis delivery West Coast India. The Pacific also gained ground, supported primarily by healthy Australian mineral demand, with an 82,000-dwt fixing at $22,000 to South China, a 90,000-dwt fixing at $24,000 to Japan, and an 81,000-dwt fixing at $20,500. Indonesian activity remained steady, with a 76,000-dwt fixing at $17,000 for a trip to South China. North Pacific conditions showed signs of stabilising, although increasing tonnage availability tempered optimism, with an 82,000-dwt fixing at $19,750 for a round trip to Japan. Period activity remained limited, with an 83,000-dwt reportedly fixing for 11–13 months at around $19,500.

Ultramax/Supramax
A subdued week with a few holidays and Eisbein this week saw rates under pressure. North America managed to turn the tide and rates began to recover with two 63,000-dwt vessels reported for petcoke to India at $34,000 and $34,500, and a 52,000-dwt achieving $28,000 from Port Arthur to Iskenderun with petcoke, having seen a 63,000-dwt fixed for grains to China at a disappointing $27,000 via Cape of Good Hope earlier in the week. Continent activity was greatly reduced compared to previous weeks, although a 60,000-dwt still agreed a strong $36,000 basis delivery Tilbury for scrap to the East Mediterranean, and the Mediterranean was also slow albeit with relatively low tonnage availability. The south Atlantic appeared devoid of early stems, although demand for end November/early December looked healthier. After supporting the market for weeks, Asia also saw increased tonnage with NoPac grains slowing and backhaul trades unable to support the market any longer, with a 63,000-dwt fixed from North China to West Africa with steels/generals at $26,000, whilst Southeast Asia saw tonnage from India/Chittagong increasingly competing and pushing rates lower. The Indian Ocean was hit hardest as it was bereft of fresh enquiry, with rates under severe pressure, with a 57,000-dwt fixed from Richards Bay to Pakistan with coal at $21,500 plus $215,000 ballast bonus. There was very little period chat, however a 61,000-dwt open West Coast India for mid-November was rumoured fixed for one year in the $18,000s.
Handysize
The market remained generally quiet over the week, with limited fixing information and mixed regional sentiment. The Continent and Mediterranean gained support from fresh activity and tightening tonnage. A 36,000-dwt vessel open Constanza on 2–5 November was fixed for a trip via the Black Sea to Poland with urea at $12,250. The US Gulf also showed signs of strengthening as improving cargo flows and a shortage of prompt tonnage supported sentiment. A 39,000-dwt vessel open Wilmington was fixed for delivery Savannah in mid-November for a trip to the Continent with pellets at $21,000. By contrast, the South Atlantic remained soft throughout the week, with limited fresh demand keeping rates under pressure and prompting both owners and charterers to lower their expectations. A 28,000-dwt vessel open Tema on 1–7 November was fixed for a trip via Recalada to Algeria with grains at $14,000. In Asia, activity remained muted and rates were broadly flat, with little clear direction. A 35,000-dwt vessel open Thailand was placed on subjects for a trip to Japan in the $18,000s.
Clean
LR2
The TC1 75kt MEG/Japan index eased by eight points this week to WS1005, while the corresponding Baltic round-trip TCE edged up by $100 to $292,000/day. For the TC20 90kt MEG/UK-Continent run, the index dropped by $2.21 million to $19.29 million, corresponding to $297,300/day on Baltic round trip. The TC15 80kt Mediterranean/East index shed $1.70 million to finish at $9.25 million, with the Baltic round-trip TCE falling by $20,400 to $79,200/day.
LR1
The TC5 55kt MEG/Japan index slipped by nine points this week to WS1025, translating to $212,300/day on Baltic round trip. For a trip westward on the TC8 65kt MEG/UK-Continent route, the index dropped by $1.58 million to $14.75 million, while the Baltic round-trip TCE return declined by $27,600 to $223,700/day.
MR
The TC17 35kt MEG/East Africa index edged down by five points this week to WS896, although the TCE increased by $1,000 to $113,900/day. On the UK-Continent, the TC2 37kt ARA/US Atlantic Coast index shed 22 points to WS206, with the corresponding Baltic round-trip TCE falling by $3,300 to $13,600/day. In the US Gulf, the TC14 38kt US Gulf/UK-Continent index dropped by 47 points to WS429 and the round-trip TCE declined by $8,500 to $60,800/day. The TC21 38kt US Gulf/Caribbean run fell by $157,100 to $1.47 million, with the corresponding Baltic TCE decreasing by $8,500 to $60,600/day. The MR Atlantic Triangulation Basket TCE dropped from $82,100/day to $72,000/day.
Handymax
In the Mediterranean, the TC6 30kt Cross-Mediterranean index lost 73 points to WS448 this week, with the corresponding Baltic round-trip TCE dropping by $20,200 to $88,100/day. The TC23 30kt Cross UK-Continent index shed 79 points to WS420, while its TCE fell by $22,400 to $78,500/day.
VLCC
VLCC rates on the Baltic Exchange routes headed down this week. The TD3C route (270,000 mt Middle East Gulf/China) has fallen almost 47 points since last Friday to WS1220.63, producing a daily round-trip TCE of $1,303,616 for the standard Baltic VLCC. TD34 (Gulf of Oman/China) fell more sharply, losing almost 86 points to WS586.43, giving a round-trip TCE of $619,969/day.
In the Atlantic market, the rate for the 260,000 mt West Africa/China route (TD15) lost 77.5 points to WS564.38, producing a round-trip TCE of $561,731/day. Meanwhile, the US Gulf/China route (TD22) fell by over $5.7 million to below the $58 million mark, resulting in a daily round-trip TCE of just below $451,000.
Suezmax
The Suezmax market has started to rebalance, with rates falling sharply across all the Baltic Exchange routes. The rate for the 130,000 mt Nigeria/UK Continent voyage (TD20) fell by over 270 points (38%) to WS430, giving a daily round-trip TCE of about $224,500. The TD27 route (Guyana/UK Continent, basis 130,000 mt) dropped more sharply, losing 318 points (45%) to WS382.22, producing a daily round-trip TCE of just over $198,400. The 145,000 mt US Gulf/UK Continent route (TD33) fell further, losing 321 points (52%) to WS292.78, giving a round-trip TCE of a little over $172,200/day.
In the Black Sea, the 135,000 mt CPC/Augusta route (TD6) tumbled almost 274 points (29%) to WS664.44, producing a daily round-trip TCE of just under $513,400.
Aframax
In the North Sea, the rate for the 80,000 mt Cross-UK Continent route (TD7) tumbled 212.5 points to WS350, giving a daily round-trip TCE of just below $242,600 basis Hound Point/Wilhelmshaven.
In the Mediterranean, the rate for the 80,000 mt Cross-Mediterranean route (TD19) collapsed almost 373 points to WS300. Basis Ceyhan/Lavera, this produces a daily round-trip TCE of about $100,300.
Across the Atlantic, rates fell heavily. The 70,000 mt East Coast Mexico/US Gulf route (TD26) fell 288 points to WS408, giving a daily round-trip TCE of close to $122,000. The 70,000 mt Covenas/US Gulf route (TD9) also dropped almost 290 points to WS397, producing a daily round-trip TCE of just over $111,100.
The 70,000 mt US Gulf/UK Continent route (TD25) plunged over 295 points to the WS399 mark, giving a round-trip TCE, basis Houston/Rotterdam, of about $107,500/day.
On the Vancouver export routes, rates weakened again. The TD28 route (80,000 mt crude oil Vancouver to China) fell by $1.88 million to $10.15 million, producing a round-trip TCE of under $206,200/day. The TD29 route (80,000 mt crude oil Vancouver to Pacific Area Lightering point off the USWC) fell 104 points to WS783.
LNG
The LNG market strengthened this week, with relatively high fixing activity east of Suez helping to tighten vessel availability. The Atlantic also saw a gradual improvement in spot rates, although cargo demand remains relatively subdued and the tonnage list continues to limit further upside.
On the BLNG1 Australia–Japan route, rates increased by $9,600 week-on-week to settle at $54,600/day. Increased fixing activity and a tightening pool of available vessels supported rates throughout the week.
The BLNG2 US Gulf–Continent route increased by $5,700 to close at $35,300/day. Rates gradually firmed as some tonnage was absorbed, although subdued demand and continued vessel availability kept the increase measured.
Similarly, the BLNG3 US Gulf–Japan route gained $2,200 week-on-week to settle at $64,600/day. The route remained supported by tightening effective availability, although a wider bid-offer spread continued to limit liquidity.
In the time charter market, rates were mixed. The six-month rate increased by $1,700 to $44,200/day, while the one-year term rose by $200 to $54,067/day. Further out the curve, the three-year period edged lower by $100 to $70,500/day.
LPG
The LPG market firmed this week, with a healthy level of fixture activity in the West supporting rates. With further cargoes still being worked and vessel availability broadly balanced against demand, sentiment remains positive.
On the BLPG1 Ras Tanura–Chiba route, rates settled at $261.40 per tonne, with TCE earnings closing at $254,022/day.
The BLPG2 Houston–Flushing route increased by $5.33 week-on-week to settle at $180.00 per tonne, with TCE earnings rising by $9,610 to $210,924/day.
Similarly, the BLPG3 Houston–Chiba route gained $8.29 to close at $322.29 per tonne, while TCE returns increased by $10,491 to $196,055/day. The route strengthened through the week as cargo activity remained healthy and the position list stayed relatively balanced.
Container
Container freight rates were a mixed bag over the past week. The FBX Weighted Average decreased by 17 points from 3,514 at the end of last week, ending this week at 3,497.
The major trade lane from Asia into the US West Coast (FBX01) saw rates increasing by USD176, from USD8,342 at the end of last week, ending this week at USD8,518 per FEU. The Asia to US East Coast trade (FBX03) declined week on week by USD52, ending the week at USD9,848 from USD9,900 per FEU. Asia to North Europe (FBX11) saw rates decline over the week from USD3,595 to USD3,384 per FEU, a decline of USD211. The trade from Asia into the Mediterranean (FBX13) saw rates drop slightly by USD55 from USD 4,370 to USD4,315 per FEU. The biggest move of the week was (FBX21) North America East Coast to North Europe, which saw rates decline by USD221 from USD1,155 to USD934 over the week.